Forex and CFD Spreads vs Commissions: What They Really Cost You
A tight spread can still cost more once commission is added in. Here's how to compare total cost per trade instead of judging each fee alone.
By LTI BLOG Team · Updated
Forex and CFD Spreads vs Commissions: What They Really Cost You
Spreads and commissions are two pieces of the same bill, not two separate costs to weigh against each other. Comparing them one at a time, rather than adding them together, is usually where the real cost of a trade gets missed.
Most traders start by comparing whichever number looks smaller: a tight spread on one account, a low commission on another. What actually matters is the total, spread plus commission, on a like for like basis. That comparison gets clearer once you know how different account types price a trade in the first place.
Key Takeaways: • Spreads and commissions are two parts of one trading cost, not separate numbers to weigh against each other. • A spread is built into the buy and sell price you see on the platform; a commission is a separate, fixed charge added on top, usually per lot. • The only fair comparison is total cost per trade: spread plus commission, for the same instrument and the same trade size. • Tighter spreads paired with a commission usually reflect a different pricing model, closer to raw market pricing, not simply a cheaper account. • Compare cost structures using your own typical trade size and frequency, since the cheaper option depends on how you actually trade.
Risk disclosure: Trading in foreign exchange (forex), contracts for difference (CFDs), and other leveraged financial instruments involves a high degree of risk and may not be appropriate for all investors. You should only trade with funds that you can afford to lose without adversely affecting your financial position.
What a Spread Actually Is
A spread is the gap between the price you can buy at and the price you can sell at, quoted at the same instant. You don't pay it as a separate line item; it's already built into the two prices you see on the platform. That's why it's often called an implicit cost rather than a fee.
Spreads move. They tend to be tighter when a market is calm and liquid, and they tend to widen around news releases, thin overnight sessions, or sudden volatility. A published spread figure, such as an average or "as low as" number, is a reference point rather than a guarantee for every tick of every trading day.
For comparison, a heavily traded major pair like EUR/USD typically shows one of the tightest average spreads of any instrument, while a less heavily traded cross like EUR/GBP tends to sit a little wider on average, and a minor or exotic pair wider still. Whatever figure a broker publishes for a given instrument, treat it as a description of typical conditions rather than a fixed promise for every trade.
What Drives Spread Width
Spread width is not set arbitrarily. It mostly reflects how liquid the underlying market is at that exact moment, meaning how many buyers and sellers are actively quoting prices for that instrument. When many participants are active, such as during the overlap between the London and New York trading sessions for major currency pairs, competition between liquidity providers tends to pull spreads tighter. When fewer participants are active, such as late in the Asian session or right before a major holiday, the same pair can show a noticeably wider spread simply because there is less competing liquidity to draw on.
Scheduled news events add another layer. Ahead of a major data release, such as a central bank rate decision or a jobs report, liquidity providers often widen their own quotes to protect against sudden price gaps, and that gets passed straight through to the spread you see. This is a temporary, predictable pattern tied to the economic calendar rather than a sign of anything wrong with the platform.
Instrument type matters too. Major currency pairs with deep, constant trading volume carry the tightest spreads as a rule. Minor pairs, exotic currencies, and commodity or index CFDs generally carry wider spreads, reflecting thinner underlying liquidity rather than a deliberate markup.
How a Commission Works
A commission is a separate charge added on top of the spread, usually quoted per lot and often split between opening and closing a position, a pairing generally called a round turn. Unlike a spread, it doesn't move with market conditions. It's a fixed, disclosed fee that shows up as its own line in your MT5 trading history.
Commission based pricing tends to appear on account types built around raw or close to raw spreads. The idea is that the broker passes through pricing closer to the underlying interbank market, with the commission functioning as the broker's fee for that access, rather than folding a markup into the spread itself.
Because a commission doesn't fluctuate the way a spread can, it's usually the easier of the two costs to plan around. You generally know it in advance, which makes it simpler to include in a cost calculation before you ever place the trade.
Why Total Cost Per Trade Matters More Than Either Number Alone
Looking at spread or commission in isolation can be misleading, because a lower number in one column doesn't necessarily mean a lower total cost. The only comparison that reflects reality is spread plus commission, added together, for the same instrument and the same trade size.
Consider a hypothetical standard lot (100,000 units) on EUR/USD, where a pip is worth roughly $10. A spread of 0.60 pips on that trade works out to about $6 in built in cost, with no separate commission. A different account might show a much tighter spread of around 0.10 pips, worth roughly $1, but charge a commission of $6 round turn. Add that up and the total lands close to $7, actually higher than the first example.
This matters more the more often you trade. A cost difference of even a dollar or two per round turn compounds quickly across dozens or hundreds of trades a month, in a way that's easy to overlook when you're only glancing at the spread column.
Why Tighter Spreads Often Carry Higher Commission
Tighter spreads paired with a commission usually reflect a different pricing model rather than a straightforward discount. Accounts built for raw or deep liquidity pricing, sometimes labeled ECN style, generally pass through spreads closer to the interbank market and recover the broker's margin through commission instead of through the spread itself.
That trade off isn't automatically better or worse. It depends on how large your positions are and how often you trade. A trader placing fewer, larger trades may find the commission based structure works out cheaper overall, while a trader placing frequent, smaller trades might find a wider spread with no commission simpler to plan around, even if the headline spread number looks less attractive.
Account minimums often track this distinction too. Entry level accounts with balanced spreads and low or no commission tend to have lower minimum deposits, while raw spread, commission based accounts aimed at more active or higher volume trading generally require a larger minimum deposit to open.
London Trading Index structures its own two account types around exactly this trade off:
- Core account: balanced spreads, no commission, and a lower minimum deposit, built for traders who want a simple, predictable cost with nothing else to calculate.
- ECN account: raw spreads plus a commission, and a higher minimum deposit, built for traders who place larger or more frequent trades and want pricing closer to the underlying market.
Neither structure is better in the abstract. The right one depends on your own trade size and how often you trade, which is exactly the comparison the next section walks through. Full current figures for both account types are set out on the trading conditions page.
How to Work Out Your Own Cost Per Trade
Start by pulling the published spread for the instrument you actually trade, not a headline figure for a different pair. Spreads vary meaningfully across instruments, so a tight EUR/USD spread tells you nothing reliable about GBP/JPY or a metals CFD.
Next, add any commission that applies to that account type for the same trade size, using the broker's own commission schedule rather than a rough guess. Once you have both numbers in the same currency, add them together to get a single total cost per round turn.
Finally, run that total against your typical trade size and frequency, since a cost structure that suits an occasional swing trade can look very different once applied to dozens of trades a week. Rechecking this occasionally is worth doing too, since published spreads are usually shown as averages or "as low as" figures that can shift with market conditions.
Where to Find the Full Cost Breakdown
The specific spread and commission figures for each account type, along with how they apply across instruments, are set out on London Trading Index's Trading Conditions page rather than summarized here. That's the page to check before assuming how a given account type prices a particular trade.
Spread and commission are only part of what a trade costs over time. Swap charges on positions held overnight, slippage during fast moving markets, and the extra cost of trading more often just to chase a tighter number can all add up in ways that aren't obvious from a spread table alone. Costs are one input into a trade's outcome, not the whole picture, which is exactly why they're worth getting right rather than treating them as an afterthought.
Frequently Asked Questions
Is a zero spread account always cheaper?
Not necessarily. A zero or near zero spread almost always comes with a commission attached, and once you add the two together the total cost can end up similar to, or higher than, a wider spread account with no commission.
Do commissions change during volatile markets?
Generally no. Commission is usually a fixed, disclosed amount per lot, whereas spreads are the part of the cost that tends to widen during news events or thin liquidity.
Can I switch account types if the cost structure doesn't suit my trading?
Usually yes, though it depends on the broker's process and any minimum deposit requirements for the account type you want to move to. It's worth checking the specific terms directly with LTI's support team before assuming a switch is automatic or instant.
Why do published spreads sometimes show a range instead of one fixed number?
Because spreads move with market liquidity throughout the day. A broker's "average" or "as low as" figure describes typical conditions across a period of time, not a number that holds for every single trade, which is why the spread you get on a calm afternoon can differ from the spread you get seconds before a major data release.
*This article is general information about CFDs, leveraged products and instruments, and trading. It is not investment advice, a recommendation, or an offer to trade, and it does not take account of your objectives, financial situation or needs. Refer to the footer for the full disclaimer, terms and policies.
Related Articles
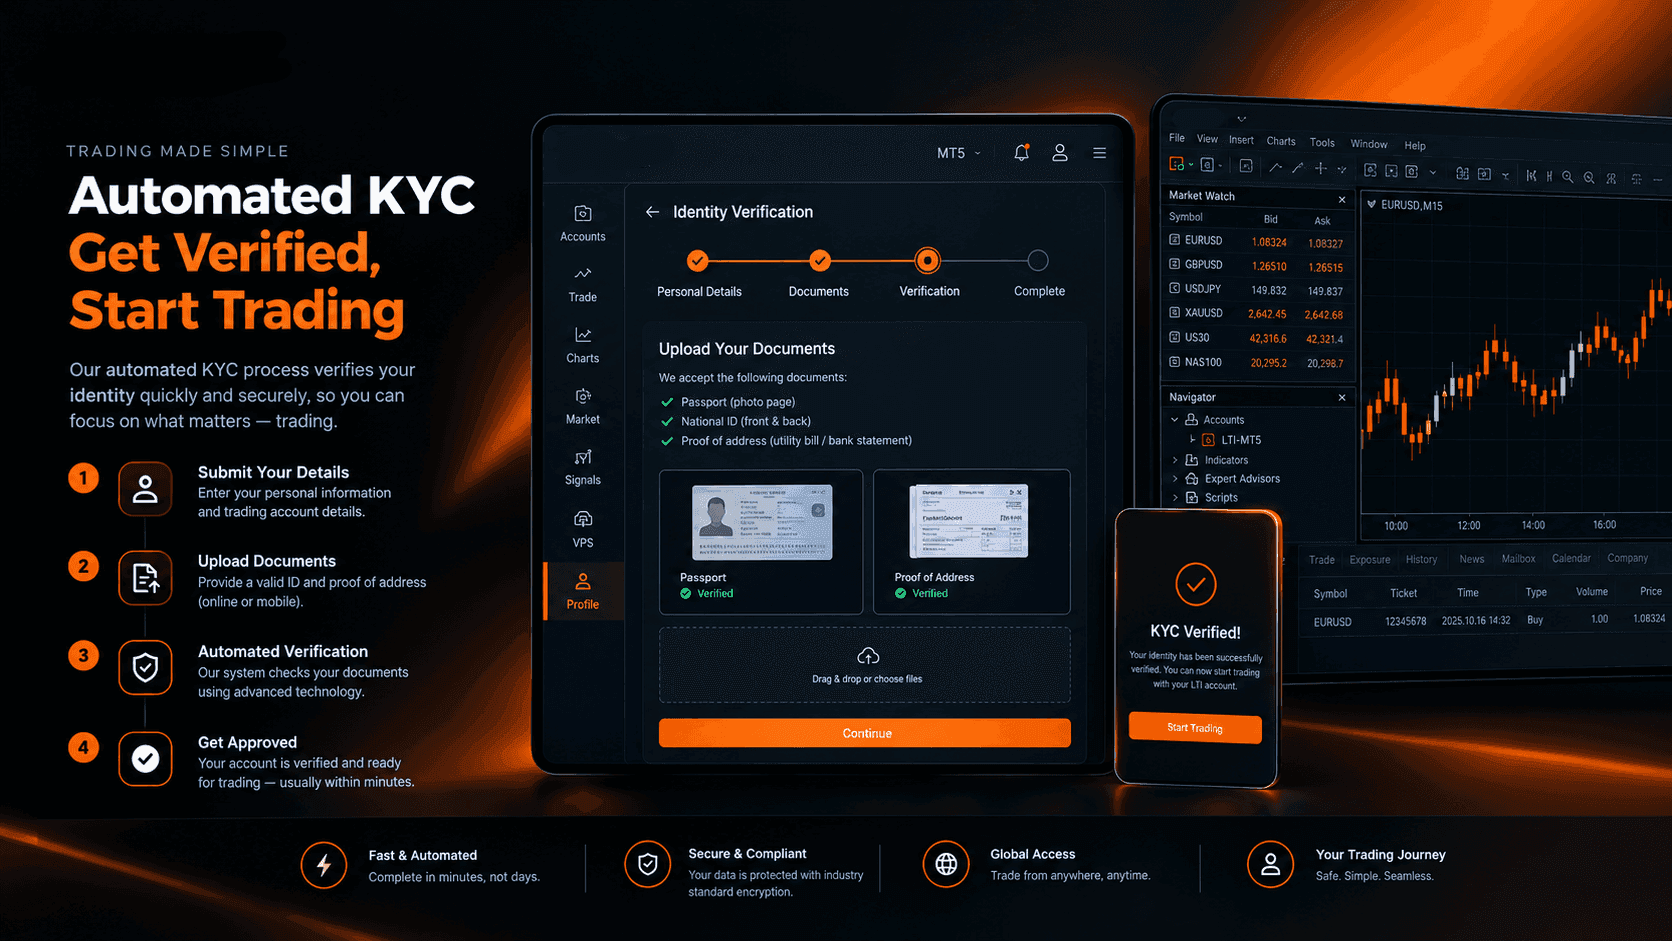
How Automated KYC Verification Actually Works at LTI
KYC verification is required before you can trade with LTI, not optional. Here's how the automated process works and how fast it can be.
Read Article
Copy Trading, PAMM, and MAM: What's the Difference?
Copy trading, PAMM, and MAM handle risk differently. Here's what actually separates the three account structures.
Read Article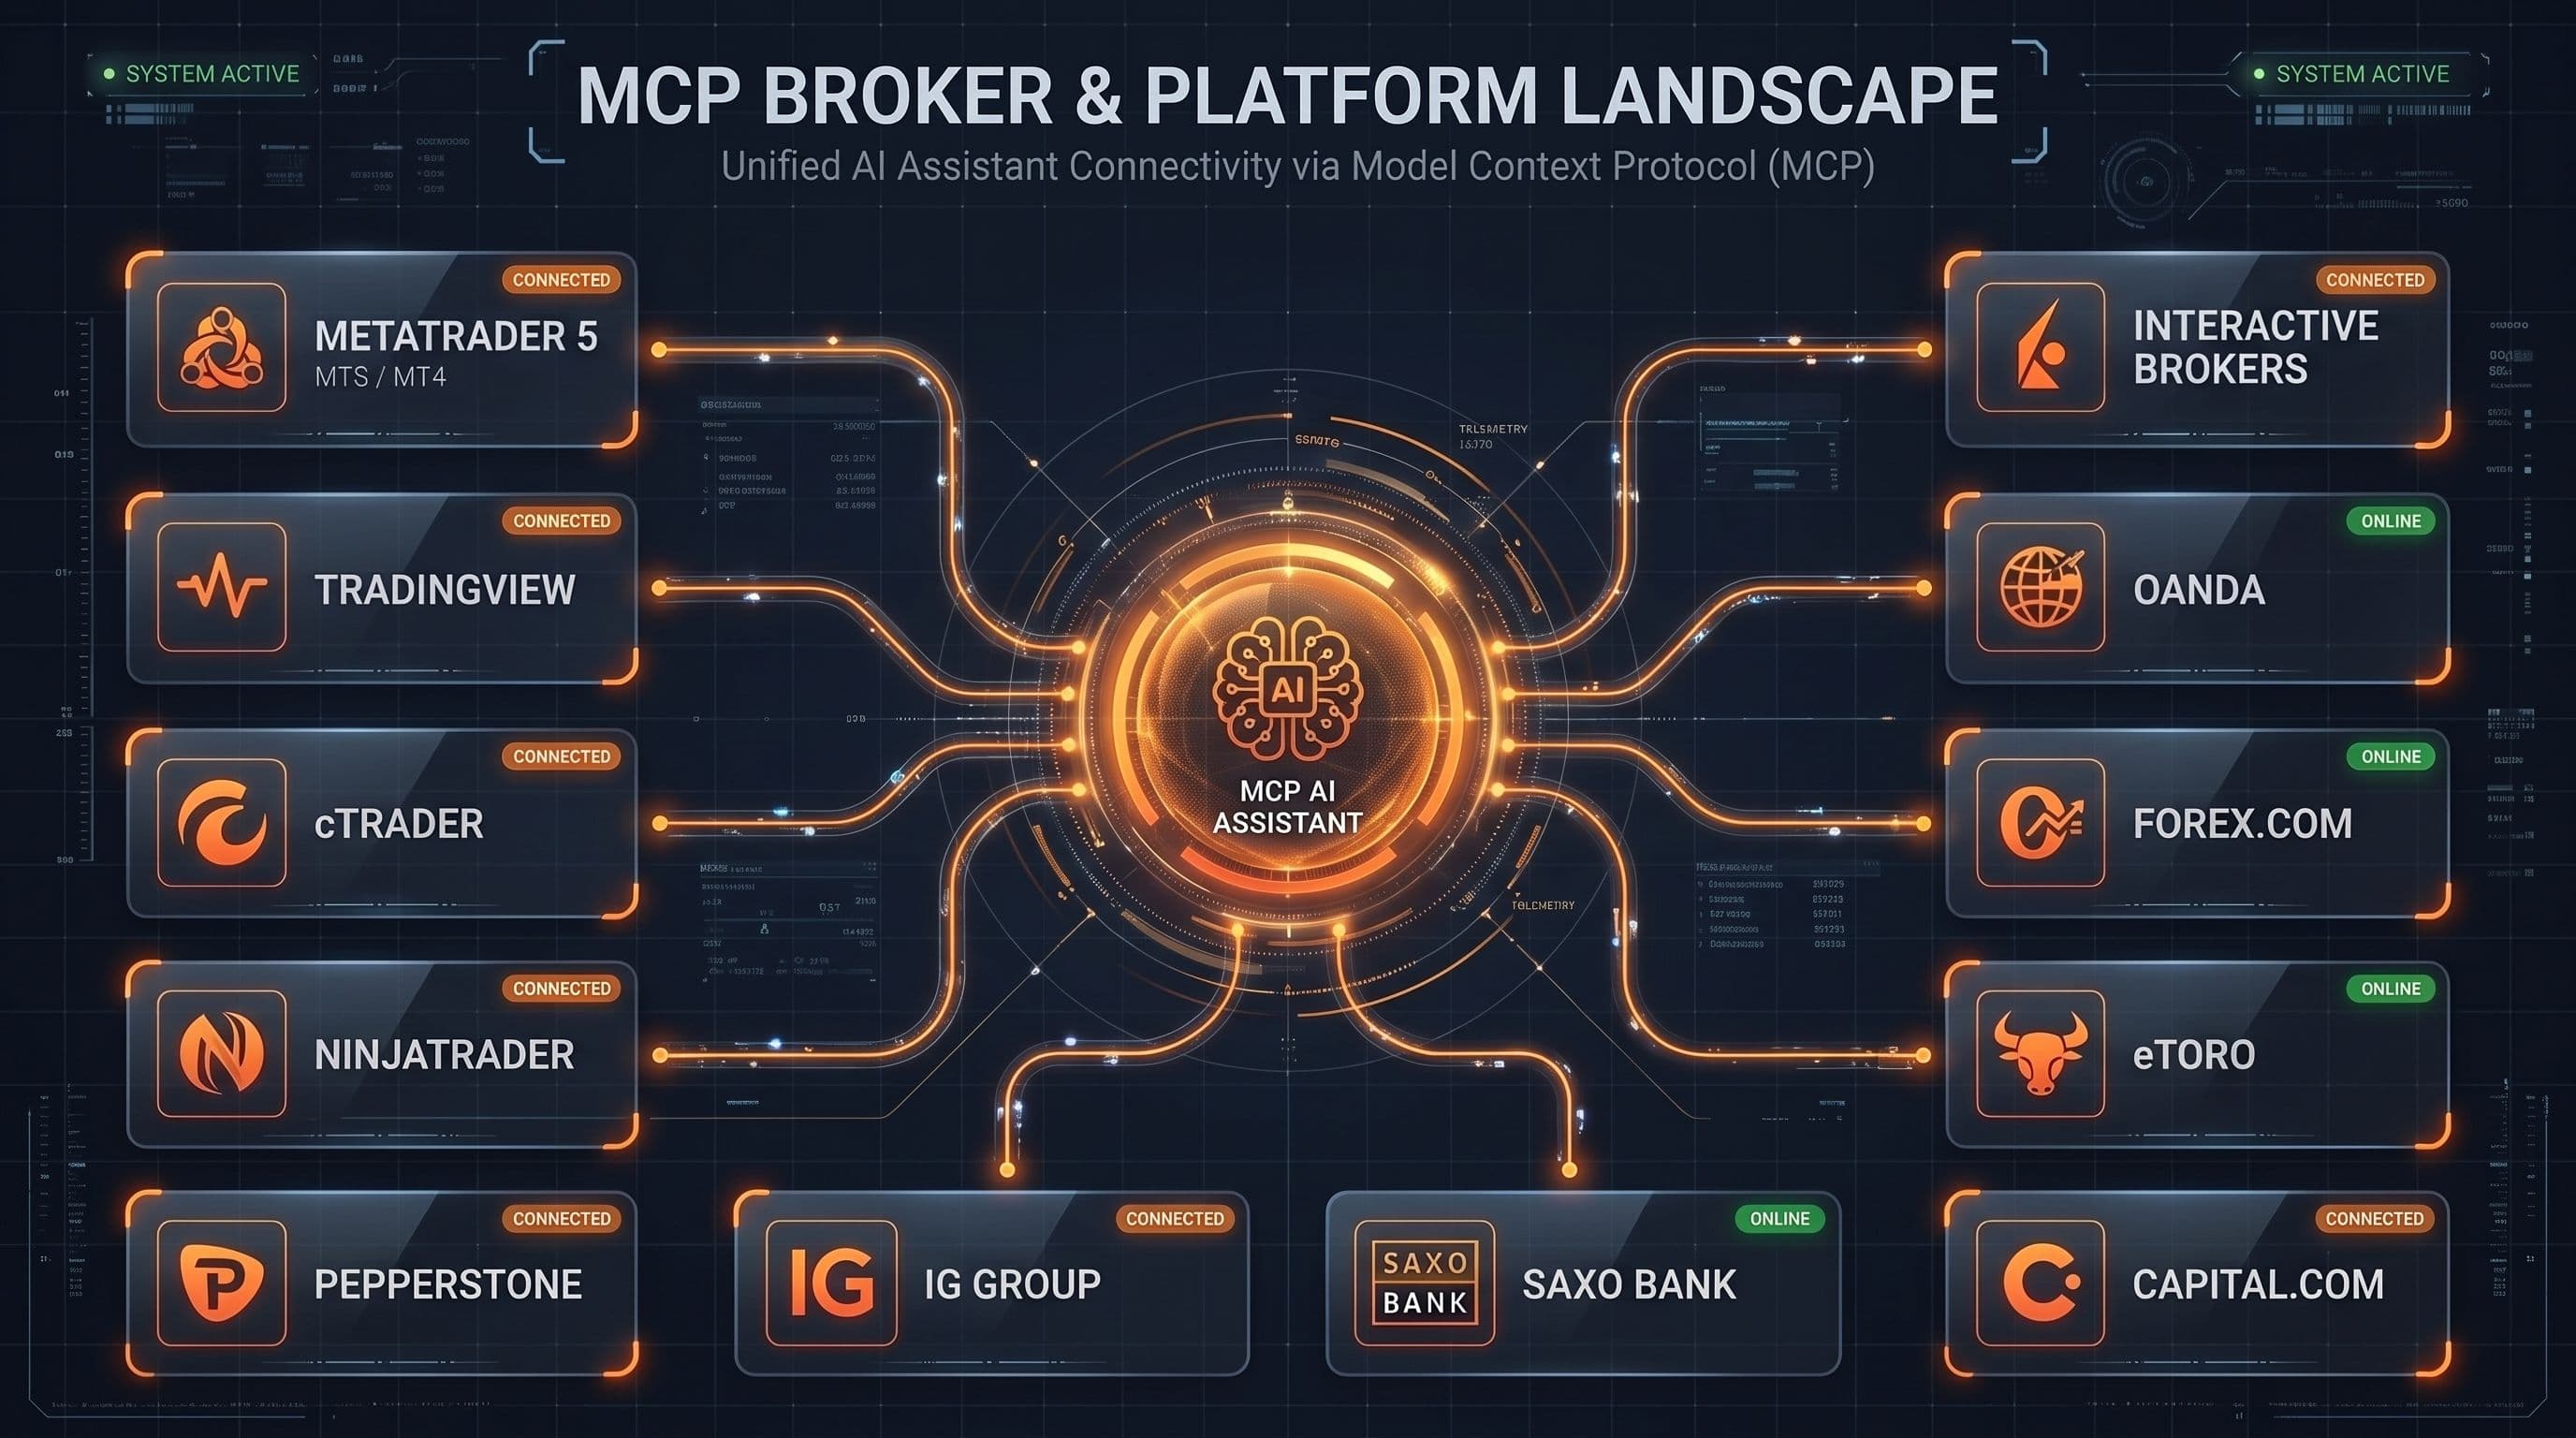
The Broker MCP Race: Every Broker and Prop Firm That Has Opened Up to AI Agents
A dated tracker of every forex and CFD broker, prop firm, and platform vendor that has shipped MCP or AI agent support as of September 2026, including where LTI's own MT5 integration fits in.
Read ArticleCreate Your Account
Account opening happens in the client area, and takes a couple of minutes.
*Opening an account finishes in the secure client area, where these details carry across. Already registered? Sign in, or talk to us first.
CFDs are complex instruments and come with a high risk of losing money rapidly due to leverage. 73% of retail investor accounts lose money when trading CFDs. You should consider whether you can afford to take the high risk of losing your money.